

Ualett

- 1.28K Reviews
- 4.6
- Downloads
- 500,000+
Our take on Ualett from Appgk
When I first opened Ualett, I understood its appeal quickly: it is a free finance app built around the working reality of gig workers rather than a traditional monthly paycheck. That focus matters. Someone driving, delivering, freelancing, or taking short-term jobs often needs to think about money between jobs, not only at the end of a pay period. Ualett aims to fit into that rhythm, and my first impression was that it feels more relevant to irregular earners than a standard banking app that assumes predictable income.
The app comes from Cabicash Solutions, Inc., and its store presence is encouraging without being the only reason to try it. It has an average rating of 4.6 from around 7,600 ratings, with roughly 1,300 written reviews and more than 500,000 installs. Those figures suggest that Ualett has found a real audience, especially among people looking for a finance tool connected to gig work. Still, the important question is not whether it is popular during the first week. The better question is whether it remains useful once the novelty disappears.
What Ualett feels like during the first week
The first week is when Ualett is easiest to appreciate. A gig worker usually has several financial concerns competing for attention: fuel, meals while working, phone service, vehicle upkeep, household bills, and the unpredictable timing of earnings. A finance app that acknowledges that pattern can feel more practical than one designed around a fixed salary and a single payday.
I would not approach Ualett as a complete replacement for every financial service I already use. I see it more as a focused companion for managing the money side of flexible work. That distinction is useful because it sets a realistic expectation. The app’s store summary describes it as being built for gig workers, and that specialization is its strongest identity. It is not trying to be a general-purpose financial dashboard for every possible situation.
Best Parts of Ualett
Things to Keep in Mind About Ualett
During initial use, I would pay attention to how quickly the app fits into an existing routine. The best test is not simply opening it once and browsing around. Instead, I would use it after a work shift, when income and expenses are still fresh in my mind. For example, after spending an afternoon making deliveries, I might check the money connected with that work, think about fuel used during the shift, and decide what can safely remain available for the next day. That is a more meaningful test than admiring a clean screen.
One practical advantage of a gig-focused tool is mental framing. A conventional budgeting app often asks users to organize money by broad monthly categories. That can be helpful, but it may feel disconnected when income arrives in uneven bursts. Ualett makes more sense for someone who thinks in terms of work sessions, upcoming expenses, and short gaps between payments. The difference is subtle, yet it can decide whether an app becomes a habit or gets forgotten.
News and Features Related to Ualett

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
I also like the fact that it is free to download and available to an Everyone-rated audience. That lowers the barrier for someone who wants to explore the workflow before committing money to another financial service. Free access does not automatically make an app worthwhile, of course, but it makes experimentation less stressful. A user can spend time deciding whether the app matches their working pattern instead of treating the first installation as a financial commitment.
Who gets the fastest benefit
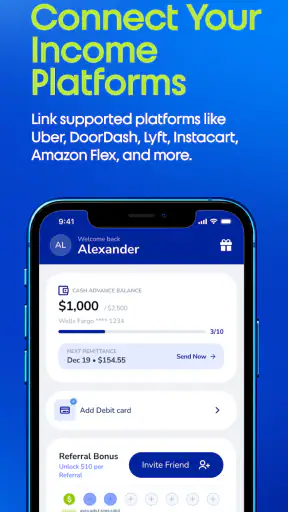
Ualett is most appealing to people whose earnings are connected to flexible or app-based work and who want a finance experience that recognizes that reality. A driver with several work platforms, a courier whose income changes from day to day, or a freelancer managing uneven payments may understand the app’s purpose immediately.
Don't want to read the full review?
The first-week benefit is smaller for someone with a stable salary, a conventional checking routine, and no need to separate work-related cash flow from personal spending. That person may find a broader banking app or a traditional budgeting tool more natural. Ualett’s focused approach is a strength only when the user’s financial life actually resembles the audience it targets.
There is also a useful psychological test: does the app help you make a decision? If it merely shows financial information that you already know, it may not earn a permanent place on your phone. If it helps you decide whether to accept another shift, reserve money for a work expense, or avoid spending money needed for tomorrow, then it has a clearer role.
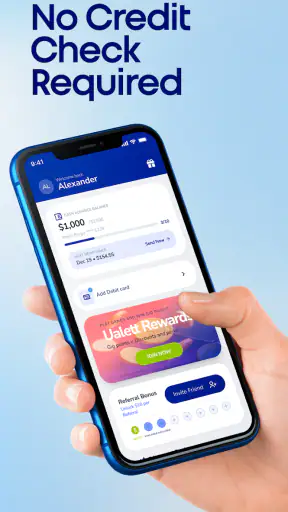
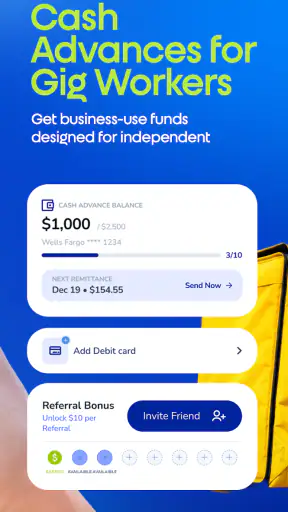
Screenshots
What remains useful after the first month
After the first month, the excitement of trying a new finance app normally fades. That is when I would judge Ualett by repetition. Can I return to it without having to rethink the whole process? Does it help me understand my working money quickly? Does it reduce uncertainty, or does it become another place where I have to manually keep track of the same information?
The strongest long-term case for Ualett is routine visibility. Gig work can make money feel deceptively available because earnings arrive in small or irregular amounts. A worker may see cash coming in and forget that fuel, taxes, maintenance, subscriptions, and personal bills are also competing for it. A specialized app can be valuable if it keeps those competing priorities visible at the moment decisions are made.
My suggested monthly routine would be simple. I would check Ualett at the beginning of a work period, briefly review it after several shifts, and use it before a larger personal purchase. The goal would not be to stare at the app every day. The goal would be to create a repeatable checkpoint. This is one of the more important trade-offs: a finance app should support a habit, not demand constant attention.
That approach also helps answer whether the app deserves lasting space. If Ualett becomes the place where I quickly understand work-related cash flow, it has recurring value. If I only open it when I remember that I installed it, its usefulness is probably limited. The app cannot create financial discipline by itself; it can only make a disciplined routine easier to maintain.
Compared with a regular banking app, Ualett’s likely advantage is relevance to gig work rather than breadth. A bank app may be better for account management, transfers, statements, and a wider set of conventional services. Compared with a general budgeting app, Ualett may feel more immediately connected to flexible income. The trade-off is that a general budgeting tool can sometimes offer a broader view of household finances, while a specialized app may be less satisfying if the user wants one place for every financial category.
For that reason, I would not automatically delete a bank app or a budgeting app after installing Ualett. I would give each one a clear job. Ualett can be the work-focused view, while a bank remains the place for ordinary account tasks and a broader budget tool handles household planning. Keeping those roles separate may sound less convenient, but it can prevent one app from becoming cluttered with information that does not help a gig worker make immediate decisions.
A realistic everyday test
Imagine a courier who works several short shifts during a busy week. On Monday, the courier earns money but also spends on fuel. On Wednesday, the car needs attention, and the courier has to decide whether to work another evening or protect cash for the repair. By the weekend, a household bill is due. In that situation, Ualett is useful only if it helps connect the earnings from work with the expenses and timing that surround them.
I would use that scenario as a month-long test. After each shift, I would make the smallest reasonable update or review, rather than trying to reconstruct the entire week later. Before taking an extra shift, I would check whether the expected benefit still made sense after work-related costs. Before a personal purchase, I would remember that irregular income can look healthier than it really is. This workflow is not flashy, but it is where a gig-focused finance app can earn its place.
A non-obvious benefit of this approach is that it separates “money earned” from “money available.” Those are not always the same thing for a gig worker. Treating them as identical is an easy way to create stress later. Ualett is most valuable when it encourages that distinction without making the user build a complicated spreadsheet after every shift.
The maintenance burden and where fatigue begins
No finance app is completely effortless. The main maintenance question is how much attention Ualett requires before it provides useful information. If I have to repeatedly enter details, correct records, or move between several services to keep the picture accurate, the routine may become tiring. A finance tool can be well designed and still lose its place in daily life if the upkeep feels like another job.
This is especially important for gig workers, who are already managing schedules, routes, customers, equipment, and changing demand. A workflow that feels manageable on a quiet day may become irritating during a long shift. I would therefore judge Ualett by its lowest-energy use case: can I check or update what matters when I am tired, busy, or between jobs?
Another source of fatigue is fragmented financial attention. If Ualett is used alongside a bank app, payment services, work platforms, and a separate budgeting system, the user may eventually wonder which screen contains the most reliable picture. That does not make Ualett a poor choice, but it does mean the app needs a clearly defined role. I would avoid duplicating every piece of information across multiple tools. Instead, I would decide which service is the authority for each task.
There is also a habit problem that affects specialized finance apps: users may open them only when money feels tight. That turns the app into an emergency tool rather than a planning tool. I think Ualett works better when checked during ordinary weeks too. A short, regular review can reveal spending patterns before they become urgent. Waiting until the account feels uncomfortable makes any finance app seem less helpful than it might be.
The current version is 2.73.0, and it supports devices running Android 8.0 or later. That makes the compatibility question straightforward for many Android users, but anyone with an older device should check the operating system before planning around it. I would also keep the app updated when practical, particularly for a finance product where reliability matters more than having a rarely used application sitting unchanged on a phone.
Ualett should not be the only place I keep important financial awareness. I would still review the original records connected with work and payments, especially when something looks unusual. A focused app can simplify a routine, but it should not encourage blind trust. The sensible workflow is to use it for clarity and habit, then verify important decisions against the underlying account or work information.
When another option is the better fit
I would steer a person toward a traditional banking app if their main need is full account servicing rather than gig-work organization. I would choose a broad budgeting app for someone who wants detailed household planning across many categories, long-term goals, and a wider financial picture. I would also hesitate to recommend Ualett to someone who dislikes maintaining more than one financial app.
It may also be the wrong choice for a worker whose income is already predictable and whose current system is working well. Adding a specialized tool simply because it is designed for gig workers can create duplication without solving a real problem. The right question is not whether Ualett has a distinctive audience; it is whether the user’s current money routine has a gap that this app can fill.
For new gig workers, I would recommend starting with a narrow purpose instead of trying to organize everything at once. Use Ualett to understand work-related cash flow first. Once that habit feels stable, decide whether it deserves a larger role. This prevents the common mistake of filling a new finance app with every possible detail, becoming overwhelmed, and abandoning it before its useful patterns have time to appear.
My long-term verdict on Ualett
Ualett earns a lasting place for me when I treat it as a focused tool rather than a universal financial command center. Its best quality is its clear attention to gig workers, a group that often has to make financial decisions around irregular earnings and work-related costs. That focus gives it a practical reason to exist beside a bank app or a general budget planner.
The app’s free price makes trying it easy, and its 4.6 average shows that many users have found value in the experience. Its audience is substantial enough to suggest that it is more than a passing experiment, with over 500,000 installs. Even so, popularity cannot replace a personal fit. The app will remain useful only if it reduces confusion in the user’s own routine.
My final recommendation is to give Ualett a genuine trial through several normal work cycles, not just a quick first impression. Use it after work, before spending, and during a calm weekly review. Notice whether it helps separate earned money from available money, whether its upkeep stays reasonable, and whether it gives you a decision you could not make as clearly before. Those are better tests than simply counting how often the app is opened.
Ualett is worth keeping when it turns irregular gig income into a routine you can understand and maintain. It is less convincing for people seeking a complete bank replacement or an all-purpose household budget. For the right worker, though, its specialization is not a limitation; it is the reason the app can remain useful after the first-week novelty has gone.
Ualett FAQ
What is Ualett and what can I use it for?
Ualett is a digital financial service designed to help users manage everyday money-related tasks from a mobile device. Depending on your location and account eligibility, it may provide tools such as sending or receiving money, managing payments, checking account activity, or accessing other financial services. Available features can vary by country, so review the current app description and terms before relying on it for essential transactions.
How do I create and verify a Ualett account?
After installing Ualett, you generally need to register with personal information such as your name, phone number, email address, or other requested details. The app may require identity verification using an official document, a selfie, or additional information. Make sure your details are accurate and match your documents, because incomplete or inconsistent information can delay approval or limit access to certain features.
Is Ualett safe to use for managing money?
Ualett may include standard security measures such as login protection, verification codes, encrypted connections, and account monitoring, but users should still take precautions. Download the app only from an official store, use a strong unique password, enable available security options, and never share verification codes. Before depositing or transferring significant amounts, read the privacy policy, fees, user agreement, and applicable financial protections.
Are there fees, limits, or transaction restrictions in Ualett?
Fees and limits can depend on the type of transaction, your account status, payment method, location, and any applicable promotional terms. Some actions may be free while others can involve service charges, transfer fees, withdrawal costs, exchange-rate margins, or daily and monthly limits. Check the fee schedule inside the app before confirming a transaction, since charges and limits may change over time.
What should I do if a Ualett transaction fails or my account is restricted?
If a payment, transfer, or withdrawal does not complete, first check your internet connection, balance, recipient information, verification status, and any displayed error message. Avoid repeatedly submitting the same transaction until you know whether the first attempt was processed. Save the transaction reference and contact Ualett support through the official app or website. Never use unofficial support channels or share your password and security codes.











